Perspectives on Investing

Monday, April 23, 2007

Four home runs in a row . . .

Last night, the Boston Red Sox, hit four consecutive home runs. At the time the Sox were trailing the hated New York Yankees by three runs. The four home run outburst powered the Sox past the Yanks and to ultimate victory.

Using last night's performance as an analogy for the stock market may be a bit of a reach but I'll try! And, since it's been a while since my last post, I'll be able to cover a lot of ground with it. Here goes:

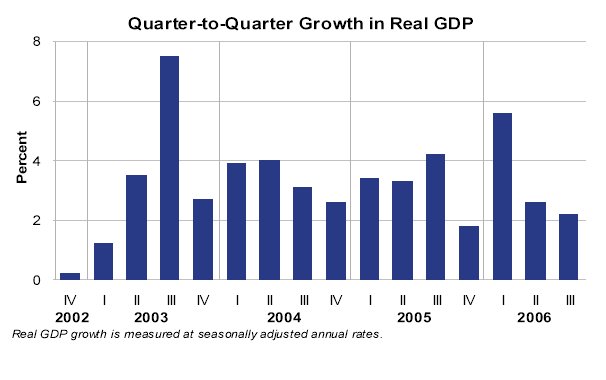
Home run #1: The Economy. Without a doubt, the economy's growth rate has slowed from last year's levels. However, the final revision of the 2006 was upward to 2.6% from 2.0% so we ended the year with a bit of momentum. We'll find out how much in just a few days as the Q1:2007 GDP preliminary report is out on the 27th. We're betting that it will be a "decent" report (say 2% give or take) albeit slowing somewhat given the rocky housing numbers and some unexpectedly poor weather - particularly in March. Remember that employment has remained strong and the unemployment rate is still low. So people are working and spending money and growing the economy.

Home run #2: Inflation/Interest Rates. Despite spikes in some commodity costs (have you bought any gas recently!) core inflation rates remain relatively subdued. While they may be a "smidge" above the Fed's comfort level, they are not spiraling out of control. We think that given somewhat slower GDP growth, continuing concerns over the subprime mortage market (and its impact on housing overall), the Fed can and will stand pat for some time to come. Stable interest rates are good for the economy and the stock market.

Home run #3: Corporate Earnings: Earnings reports are starting to flood in and, so far, companies are meeting forecasts at a rate surpassing most investors expectations. In fact, it appeared to us that last month, investors were bracing for some major disappointments. And while there have been some high profile misses, such as Yahoo! and AMD, strong reports from the likes of Google, Caterpillar, and even Intel have driven the market to new highs.

Home run #4: Buyouts galore: It seems that we start every day with at least one, multi-billion dollar buyout. While many of the buyers are private equity firms and hedge funds, we're also seeing some significant corporate buyout activity as well - witness today's by of Medimmune by AstraZeneca. The result of all this activity is a meaningful reduction in the amount of publicly traded stock. The simple law of supply and demand continues to provide uplift to our stock markets.

Bottom line? A month ago it looked like game over for the stock market. However, thanks to the four "home runs" listed above, we're once again making new highs in the Dow Jones Industrials. Time will tell if the bull market will keep its lead over the bears - but I wouldn't leave the park just yet.

Labels: , , , , ,

Sunday, February 25, 2007

Markets as forecasters

We often talk about inflation in our posts. Why? The level and direction of inflation has a very important impact on interest rates. And interest rates are a key input for valuing the stock market. Last week's dip in the market is evidence of that linkage - the CPI was worse than expected and investors sold stocks.


Thus it makes sense that if there was a way to forecast inflation with some degree of accuracy, we could make better investment decisions. Where can we find such a forecast? The usual suspects, economists, government experts, the Fed, have a spotty forecasting record which could result in some nasty surprises. So we look to the market for help. Here is a chart of the spread between 10yr US Treasury TIPS (inflation protected bonds) and traditional 10yr US Treasury bonds.


The spread provides important insights into inflation expectations. When it is rising, the market fears accelerating inflation. When it falls, the market is expecting stable to falling inflation. Notice that this spread has remained in a narrow band for about three years. And at the moment it looks like the market is not expecting a worsening inflation situation. That's good news for stocks!

Labels: , ,

Wednesday, February 21, 2007

CPI Runs Hot

After all the positive news over the past several weeks, today's report on the CPI was just a bit disappointing. Both the "headline" number of +0.2% and the "core" gain of +0.3% were above expectations and the prior three months levels. Of note, healthcare costs took a big jump - +0.8% - in January.

While not we're not happy with these numbers, we're not really concerned as one month does not make a trend break. We still believe inflationary pressures remain relatively mild and at a level the Fed can tolerate. Indeed it seems to us that we've entered a period of interest rate stability across the yield curve which should provide a favorable backdrop for the stockmarket.

Labels: , ,

Wednesday, February 07, 2007

Good News on Inflation and Growth

Recent reports out of the Departments of Commerce and Labor are encouraging for the market. Last week's GDP report and today's report on labor costs and productivity should be construed as good news for the prospects for economic growth and controlled inflation in 2007 in our view. The 3.5% rise in GDP provides a positive backdrop for business while improved productivity may ease concerns about falling profit margins and inflationary pressures - at least for the near term.

Despite some hawkish Fed comments, we don't expect significant changes in interest rates. And, the strong economic growth evident in recent reports will help support solid earnings growth in the corporate sector. Solid earnings growth and stable interest rates are usually a recipe for rising equity prices.

So, for now we're looking for stock market gains for 2007.

Labels: , , ,

Tuesday, December 05, 2006

Some better news!

Maybe there will be more than just coal in investors' stockings after some fairly positive news on the economic front today.

Labor Department data released today provided some more evidence that inflation is not spiraling out of control. Unit-labor costs were revised much lower in both the second (from +5.4% to -2.4%) and third quarter (+3.8% to +2.3%). As a result, instead of rising at a 5.3% rate over the last twelve months, unit-labor costs were revised down to a reasonable 2.9% annual gain.

Productivity figures were also revised upward to 0.2% from flat in the third quarter as initially reported. While this result was disappointing to some, we would note that the sharp slump in residential construction may be putting undue pressure on the productivity figure given that home builders either can't or won't reduce employment as fast as the decline in construction activity. We suspect that once homebuilding "normalizes" the solid productivity gains in other sectors of the economy will become more of a positive factor.

This is an important and positive report on inflation which significantly reduces the risk of further Fed rate hikes for the foreseeable future in our view. And stable rates should at least be neutral for the stock market.

On another front, the ISM services index rose to 58.9% from 57.1% in October surprising most economists - who had been expecting the index to slip to 55.8%. This is counter to the fall below 50 for last month's manufacturing figure and should assuage some fears that the economy will fall into recession next year.

Bottom line, these results should offer some comfort and joy to investors.

Labels: , , ,

Thursday, November 30, 2006

Will Santa Bring Coal To Traders This Season?

It's been a while since our last post, so I'm not going to go into great detail about all the economic numbers reported since early November. Suffice it to say that the inflation reports released before Thanksgiving were better than most expected and certainly good news for inflation watchers. I've created a link to the releases for both the PPI and the CPI if you want detail.

Yesterday (11/29/06) we got the first revision of 3rd quarter GDP. (There's one more revision on the way. Imagine trying to tell your boss you needed three tries to get your work right and keeping your job!) GDP was revised up to +2.2% versus the initial report of +1.6%. While it's clearly an improvement, 2.2% still represents a deceleration from the prior quarter. There was some good news on inflation in the report as core personal-consumption expenditure index rose 2.2% (yr./yr.) - down significantly from last quarter's 2.7% rise. This inflation number may still be high for some but at least it's heading in the right direction. And there was some impressive results on the corporate profit front with the government's number showing a 30% gain versus last year. Here's the link if you need all the gory details: Q3 GDP

Of course, all these numbers are measures of historical performance. And as investors, we're more interested in what happens next. We've seen a few numbers (Chicago PMI, new unemployment claims, and some of the housing stats, for example) that make us think that economic growth will remain subdued going forward. It's probably not a great environment to sustain the high profit growth we've seen recently but it's a good bet interest rates stay in their current range. So right now we're looking for some appreciation in stocks next year - just nothing out of the ordinary.

And what about a Santa Claus rally this December? With some of the market averages already up double digits, we somewhat concerned that Santa will have coal in his bag.

Labels: , , , ,

Monday, November 06, 2006

Employment Results Startle Analysts

This past Friday's employment report from the Labor Department has been the subject of much discussion among pundits. Not because non-farm payrolls rose a less-than-expected 92,000 in October, but because the prior two months were revised upward by a total of 139,000 jobs. September's figure alone was revised up by 97,000. (Remember how surprisingly small September's gain was initially?)

The household survey reported an impressive job growth number for October of 437,000. This was a huge increase over September's household survey number of 271,000 new jobs. And, the headline unemployment rate fell to just 4.4%.

So what should we make of these numbers?
  • First off, it's tough to be overly pessimistic about the economy near term given these results. We suspect that holiday spending will be fine despite the problems with housing.
  • Second, strong employment gains often hurt productivity over the short run and may account for some of the recent disappointment on that front.
  • Third, there is a growing shortage of labor so wage inflation will be harder to keep in check, raising doubts about any Fed rate cut in the near future.


Labels: , , ,

Thursday, November 02, 2006

No Productivity Gains in the Third Quarter

The Labor Department released productivity figures for the third quarter and they aren't very encouraging. In fact productivity for the quarter was unchanged and the prior quarter was adjusted downward significantly (read the release here). As we mentioned in a recent post, rising productivity offsets rising employment costs and helps to keep a lid on inflation. So right now, companies are not able to offset rising labor costs with productivity improvements and will either try to raise prices (bad news for inflation) or take a hit to their profit margins (bad news for earnings growth). Either way, this is not a positive for stocks.

For the optimists in the crowd, we observe that the productivity numbers can be a bit flaky as the measurement of output in some sectors is quite difficult. How does one measure the output of the financial sector for example? So wait to early December for the report on nonfinancial productivity before jumping out the window.

Labels: , ,

Wednesday, November 01, 2006

More Evidence of a Slowing Economy

Today the Institute for Supply Management (ISM) released the results of their October survey of purchasing managers - the Purchasing Managers Index (PMI). At 51.2, the index points to further growth in the economy. (Remember that any result above 50 indicates economic expansion, while below 50 indicates contraction.) However, this result was below the prior month as well as expectations, and can be construed as further evidence of a slowing economy.

A look behind the headline number provides for some interesting reading (you can access the press release here). In particular, the ISM survey on prices indicates that purchasing managers are seeing lower prices. I'm not sure how much of this relates to energy, but this has to be a hopeful sign for inflation. And, the numbers on new orders and inventories seem to indicate the potential for some further slowing in economic activity.

The ISM survey is an important indicator of the direction of economic activity. It does not help much with gauging the magnitude of the change in GDP. So based on today's release, it looks like the economy will continue to grow but we still lack clarity on the rate of growth over the next several months.

Labels: , , , ,

Tuesday, October 31, 2006

Employment Cost Index Up - Bad News for Inflation?

The Labor Department reported today that the Employment Cost Index rose 1% (or more than 4% annualized) in the third quarter and 3.3% for the latest twelve months.

Many, including myself, view the ECI as the "super core" inflation measure since employment is the predominant cost of doing business in our service-based economy. When the ECI runs above the CPI, as it is doing now, it has to raise concerns of further acceleration of the consumer price index as businesses raise prices to offset rising costs. The implications for Fed policy, interest rates and the stock market if the ECI continues to track above the CPI are not positive, in our view.

Before you panic, however, there is another key figure due out later this week - productivity. This measure of output per man-hour is a critical offset to the ECI. Simply put, if productivity grows at least as rapidly as the ECI, the chances of accelerating inflation are lessened and the pressure for the Fed to act is reduced.

Stay tuned!

Labels: , ,